

Latest InSights

Aligning Partner Compensation with Growth and Profitability in Consulting Firms
By Andy Klose - Associate Partner at Vencon Research in Berlin, Germany
Management consulting firms frequently face a critical challenge: balancing competitive partner compensation with sustainable growth and profitability. Many firms set their target on compensating partners at the market median but often fall short. This misalignment leads to partner dissatisfaction and increased pressure on leadership. Addressing the issue requires a strategic, data-driven approach that not only ensures fair compensation but also fosters performance-driven growth.
Performance and Financial Outcomes Are Interdependent
At its core, the challenge stems from a direct but complex link between partner compensation and firm profitability. Unlike salaried employees, partners derive their income largely from the firm’s profits, which in turn depend on their own ability to generate revenue and control costs. If partners underperform, firm-wide profitability suffers, making it financially unfeasible to pay them at target market levels. Therefore, increasing partner compensation requires a dual focus: boosting individual partner performance and improving overall firm profitability.
Understanding the Compensation Gap
Vencon Research regularly benchmarks partner compensation across consulting firms, comparing actual earnings to market norms and the firm’s target market percentile. A common scenario we come across involves consulting firms aspiring to pay their partners at the market median but operating closer to the 25th percentile (lower quartile). At the same time, these firms aim for ambitious double-digit revenue growth while maintaining or improving profitability.
A deeper analysis often reveals a fundamental issue: underperformance among partners, with a significant proportion failing to meet their sales targets. This raises an essential question: How can the firm enhance both partner compensation and financial sustainability?
Growth Strategies: Expanding Revenue Potential
To meet revenue growth targets, firms typically consider three strategic options:
- Increase sales targets for existing partners: While raising revenue expectations seems like a logical solution, it is often impractical if partners are already struggling to meet current targets. Without structural changes, higher sales goals would likely intensify the firm’s revenue attainment challenges.
- Increase the number of partners: Promoting internal talent or hiring externally can drive additional revenue. However, this approach is hindered if the firm’s partner compensation is not competitive, making it difficult to attract and retain top talent.
- Pursue “inorganic” growth: Acquiring smaller consulting firms can provide an immediate revenue boost, assuming the financial backing is available. Yet, without addressing underlying performance and profitability issues, mergers and acquisitions merely delay—but do not solve—the fundamental problem.
Given these challenges, what practical steps can firms take to improve both financial performance and partner satisfaction?
Rethinking Partner Compensation: Pay-for-Performance
While increasing partner pay to the target market percentile is a straightforward solution, it is rarely feasible without increasing profitability. Unlike consultant levels (below partner), where competitive compensation is often mandatory to reduce attrition, partner pay must align with contributions to the firm’s financial health.
Most consulting firms adopt a meritocratic “pay-for-performance” model. To ensure consistency, we advocate for a structured approach that integrates profit, goals, and pay within defined frameworks such as partner levels or career groups. This approach, which we refer to as the Trinity Model, links partner compensation directly to revenue and profit contributions.
Addressing Partner Underperformance
One of the key hurdles to increasing partner compensation is underperformance. Firms must take a systematic approach to improve productivity and effectiveness at the partner level. A crucial first step is conducting a book of business review to assess individual contributions and identify areas for growth. Additionally, firms should evaluate:
- Role clarity and expectations: Many underperforming partners prioritize project delivery over business development. Clarifying expectations through role definitions and accountability frameworks is essential.
- Training and development: Equipping partners with business development skills can enhance revenue generation capabilities.
- Structural realignment: Refining the firm’s partner model, including job descriptions and performance benchmarks, ensures a stronger alignment between roles and firm strategy.
Improving Profitability to Sustain Growth
Beyond individual partner performance, firms should optimize their broader business structure to enhance profitability. Key areas for evaluation include:
- Project team composition: Ensuring an optimal balance of senior and junior consulting staff improves cost efficiency.
- Firm-wide organizational structure: Adjusting the overall staffing pyramid and staff-to-partner ratios can drive margin improvements.
- Operational efficiency: Identifying cost-saving measures and optimizing service delivery models contribute to higher profits.
By strengthening both individual performance and overall firm profitability, consulting firms can create a sustainable foundation for increasing partner compensation.
A Holistic Approach to Sustainable Growth
Aligning partner compensation with market expectations requires a holistic strategy that addresses both revenue generation and profitability. By improving partner performance, optimizing the firm’s organizational structure, and reinforcing a merit-based pay model, consulting firms can create a sustainable path toward higher earnings and growth.
Additionally, enhancing compensation competitiveness will improve the firm’s ability to attract top-tier partner candidates, further accelerating growth. In the long run, improved profitability may also open doors for external financing, enabling both organic and inorganic expansion.
Ultimately, firms that successfully integrate these elements will be well-positioned to achieve their financial targets while ensuring partner satisfaction and long-term success.
We would be pleased to assist you with any additional inquiries and provide recommendations to enhance performance and financial sustainability in your organization. Contact us to learn more.
Andy Klose is an Associate Partner at Vencon Research International and heads the firm’s consulting unit.
Vencon Research International is a leading provider of compensation benchmarking and research as well as of compensation and performance-related consulting services for professional service firms, especially for audit and tax, management consulting, and IT services firms. Vencon Research International provides services to a full range of clients in more than 75 countries worldwide and is proud to name more than 85% of the world’s major consulting and/or professional services firm its clients.

Download: 2025 Expected Salary Increases in the Consulting Industry
2025 Expected Salary Increases in the Consulting Industry
These concise overviews provide:
- A consulting-specific picture, representing real estimates gathered first-hand from consulting firms in the local market.
- A picture of country wide expected salary increases, based on data from third-party research.
Our download package includes:
- Brazil
- France
- India
- United Kingdom
- United States
Vencon Research conducts compensation benchmarking studies for over 70 countries worldwide. Should you require further information on the summaries included or additional data for different countries, please contact us.

Ensuring Accurate Salary Benchmarks: Defining and Comparing Remuneration Components
By Osas Ohenhen - Business Development Manager
A well-executed salary benchmarking process follows a structured approach to ensure meaningful comparisons. Previously, we outlined four key steps that contribute to accurate and actionable benchmarking results:
- Selecting the most relevant competitors
- Identifying the most applicable “line of business”
- Conducting accurate job matching
- Comparing the relevant components of remuneration
This article focuses on the final step: ensuring a clear understanding of remuneration components before making comparisons. Without alignment on these components, salary benchmarks can lead to misleading conclusions, impacting firms' ability to offer competitive and fair compensation.
The Importance of Defining Remuneration Components
For benchmarking data to be reliable, all participants must operate on a like-for-like basis when reporting compensation. This requires standardizing definitions to ensure consistency across firms, regions, and roles. Failure to do so can result in distorted comparisons, where compensation figures appear higher or lower due to differences in what is included rather than actual market trends.
Key Remuneration Components in Salary Benchmarking

Understanding the breakdown of compensation is critical when benchmarking salaries. Below are the key components that provide a complete view of an employee’s total remuneration:
1. Basic Salary
The contractually guaranteed cash component of an employee's pay, excluding any bonuses or variable elements. This figure is typically expressed as an annual amount. Example: In the United States, the basic salary is the fixed amount an employee receives before bonuses, stock options, or benefits.
2. Allowances
Additional fixed payments that supplement basic salary, often provided to account for region-specific costs such as housing, transportation, or meal expenses. These are not typically included in bonus calculations. Example: In India, allowances may cover travel, meals, and medical expenses, significantly affecting total pay.
3. Fixed Overtime
A predetermined overtime payment included in an employee’s remuneration regardless of actual overtime hours worked. This structure is common in certain markets with strict labour laws. Example: In Japan, many companies include a fixed overtime component as part of base pay.
4. Base Salary
The sum of basic salary and allowances, providing a more complete view of guaranteed cash compensation. Example: In Australia, base salary may also include mandatory employer superannuation contributions to retirement funds.
5. Bonus (Variable Compensation)
Bonuses may be reported in two ways:
- Target Bonus: The expected variable cash bonus, typically expressed as a percentage of basic salary.
- Actual Bonus: The most recent bonus paid, reflecting realized performance-based compensation.
Example: In many markets, bonuses are tied to individual and firm performance, making them a crucial part of competitive pay structures.

Target vs. Actual Compensation: In salary benchmarking, target compensation refers to the expected or projected amount an employee is set to receive, typically based on predefined salary structures or bonus plans. In contrast, actual compensation—sometimes referred to as achieved compensation—reflects the real amounts paid in the previous year, including any variations due to performance-based bonuses, adjustments, or other discretionary elements.

6. Total Cash Compensation (TCC)
The sum of base salary and actual bonus, representing an employee’s total earnings before benefits and employer contributions.
- Target TCC (t-TCC): Expected total cash compensation, including the target bonus.
- Actual TCC (a-TCC): Total cash compensation actually paid in the prior year.
Example: In Switzerland, TCC reflects both base salary and the variable bonus awarded based on company performance.
7. Total Cost-To-Company (CTC)
A broader measure that includes base salary, variable cash bonuses, and the employer’s cost of benefits such as pension contributions, health insurance, and other mandatory employer payments.
- Target CTC (t-CTC): The anticipated total employment cost to the firm.
- Actual CTC (a-CTC): The total cost incurred in the prior year.
Example: In South Africa, CTC includes employer contributions to retirement funds and medical aid, providing a more comprehensive view of total compensation.
Vencon Research’s Approach to Defining and Comparing Remuneration Components
Vencon Research ensures clarity and consistency by standardizing how remuneration components are defined and reported. Our benchmarking reports provide detailed data on all relevant compensation elements for both the current and previous years, allowing firms to track market trends accurately.
Why Vencon Research Stands Out
Vencon Research’s methodology offers consulting firms a significant advantage by ensuring robust and reliable salary benchmarks. Key differentiators include:
- Comprehensive Data Coverage: Our reports account for all major remuneration components, preventing inconsistencies that could skew comparisons.
- Year-over-Year Comparisons: We provide both current and historical data, helping firms analyse compensation trends over time.
- Tailored Insights for Consulting Firms: Our benchmarks are designed specifically for strategy consulting firms, ensuring relevance and accuracy.
- Market Intelligence Beyond Compensation: We offer insights into broader pay trends, helping firms align their compensation strategies with evolving market standards.
- Unmatched Expertise in Job Matching: Unlike many providers, Vencon Research prioritizes accurate job matching, ensuring that benchmarking comparisons are made between truly equivalent roles.
Agreeing on and properly comparing remuneration components is essential for effective salary benchmarking. Misalignment in definitions can lead to inaccurate market positioning and difficulty in attracting and retaining talent. By leveraging Vencon Research’s structured approach and industry-specific insights, consulting firms can ensure their compensation practices remain competitive, equitable, and aligned with market expectations.

Global Outlook: Expected Salary Increases for 2025
Analysis by Irina Kvirikadze - Senior Manager, Data Integrity Lead
Competitive compensation remains essential for attracting, retaining, and motivating top talent—crucial for delivering client value and sustaining long-term growth into 2025.

Research from Vencon Research and other sources shows that while consulting salaries continue to rise in 2025, the pace of increases has slowed compared to previous years. Firms are regularly adjusting their compensation structures in response to economic conditions, technological advancements, shifting client expectations, and overall business strategy.

Our data indicates that average global salary increases in 2025 stand at 4.5%, with inflation at 2.6%—both lower than the 2024 projections of 5.4% salary growth and 3.1% inflation.
Across regions, the range is narrow, from 4.1% in Europe to 5.6% in the Middle Eastern and African countries analysed. The range of inflation rates is even tighter, from 2.4% to 2.8%.

Expected Regional Salary Growth Projections: Europe
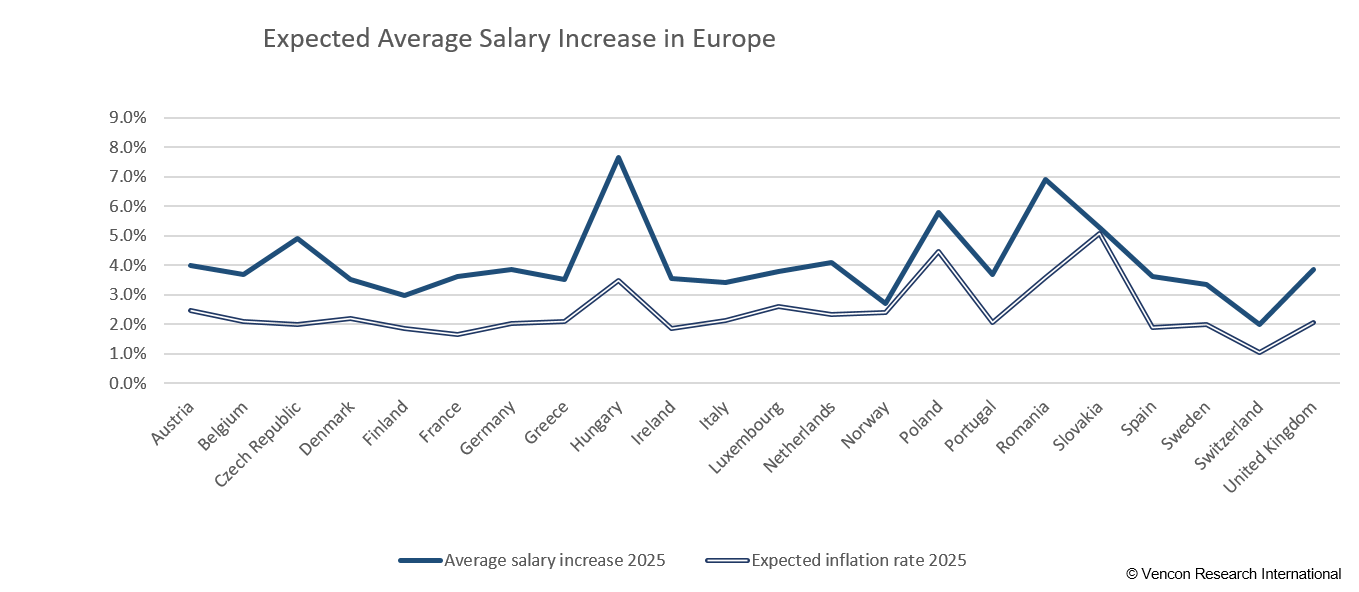
In 2025, salary increases across Europe are expected to range from 2% to 7.6%, while inflation rates are projected between 1% and 5.1%. Overall regional salary growth is forecast between 4.1% and 5.1%, with inflation ranging from 2.4% to 2.8%.
Our country-specific projections indicate 3.6% salary increases in the United Kingdom, 3.9% in Germany, 3.6% in France 3.6%, and 3.6% in Spain.
Expected Regional Salary Growth Projections: Americas
In 2025, salary increases across the Americas are projected to average 4.4%. Excluding Argentina, where hyperinflation distorts salary trends, Latin America is expected to see the highest wage growth in Colombia (6.1%), Mexico (5.4%), and Brazil (5.3%).
In North America, projected salary increases are more moderate, with Canada expected to see a 3.6% increase, while the United States is forecast at 3.7%.

Expected Regional Salary Growth Projections: APAC and MENA
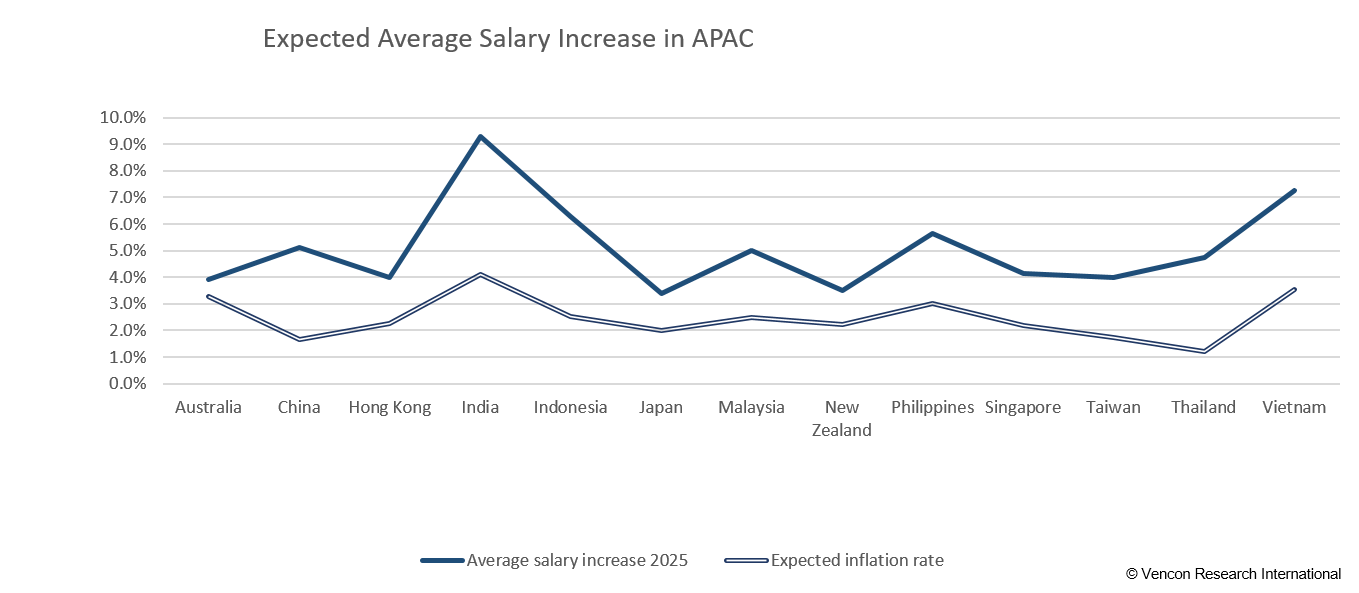
According to our research, most locations in the APAC region are expected to maintain real salary growth rates similar to those seen in the previous year. Additionally, the region is projected to experience some of the lowest inflation rates globally. However, India stands out as a leader in salary growth, with an anticipated 9.3% increase.
In the Middle East and South Africa, average salary increases are expected to be lower than last year but will still remain strong throughout 2025. Projected increases include 4.2% in Saudi Arabia, 5.9% in South Africa, and 3.8% in the United Arab Emirates.

Trends Influencing Salary Changes in 2025
Economic Slowdown and Company Performance
Despite overall salary growth, some consulting firms are moderating salary increases in response to economic slowdowns and declining deal activity, which traditionally drive industry revenues. As a result, firms are increasingly adopting a balanced approach—while base salaries continue to rise, performance-based bonuses may be adjusted downward, particularly in firms that rely heavily on transaction-driven consulting services. This shift reflects a broader focus on cost management and financial sustainability amid uncertain market conditions.
Demand for Digital and AI Expertise
Market dynamics, driven by digital transformation, are pushing up salaries for consultants with expertise in AI, big data, and cloud/cyber technologies. Major firms, including top-tier strategy consulting firms and the Big Four, are making significant investments in AI and data driven consulting solutions. As a result, professionals with strong tech and analytics capabilities are commanding premium salaries.
Demand on Expertise in Sustainability
As businesses increasingly prioritize sustainability and environmental, social, and governance (ESG) strategies, consultants specializing in these areas are seeing salary premiums. Firms are expanding their ESG consulting departments, creating new opportunities for professionals with expertise in sustainability initiatives and triggering subsequent effects on staffing and compensation packages.
Emerging Industry Trends and Competitive Landscape
While established consulting firms maintain their dominance through structured practices and global scale, emerging players and boutique consultancies are gaining traction by focusing on niche sectors and delivering agile, customized solutions. This shifting competitive landscape is fuelling salary growth, as firms compete for top talent with competitive compensation and enhanced benefits. As demand for specialized expertise rises, consultants with sought-after skills and deep industry knowledge are increasingly able to negotiate higher salaries and more lucrative opportunities.
Vencon Research provides consulting firms with precise, industry-specific compensation benchmarking, ensuring they stay competitive in a rapidly evolving market. Our research includes further detailed insights into salary increases for 2025 by country, line of business, and career level, helping firms understand pay trends and make informed compensation decisions.
Learn more about how Vencon Research can support your firm’s pay strategy.

The Management Consulting Landscape in 2025: Trends and Challenges in HR
The management consulting industry is witnessing several transformative trends, driven by technological advances, evolving client expectations and strategic shifts within organisations.
Vencon Research has prepared an overview of the key trends currently shaping the landscape and the challenges being faced by the industry in 2025, specifically with regard to human resources management.
Authors:
Erwin Harbauer is Managing Director and founder of Vencon Research International
Hilmar Albers is Partner of Data Integrity at Vencon Research International
Andy Klose is Associate Partner and Advisory Leader at Vencon Research International
1. Emphasis on Specialised Expertise
Clients are increasingly looking for consultants with deep industry knowledge and specialised skills. The traditional model of “generalist” consulting is giving way to a demand for experts, who can deliver measurable results and adapt to clients' evolving capabilities. Consultancies are expected to refine their service offerings in order to deliver more targeted and impactful solutions.
This shift however requires the recruitment of a new breed of staff, often being recruited from sources outside of the current pool of top-MBA universities. Furthermore, this trend is however also creating significant disruption within traditional consulting companies, where the newly defined specialist roles are expecting access to senior leadership positions and/or partnership.
2. Integrating Artificial Intelligence (AI) and data-driven decision making
Advanced analytics, big data, and predictive modelling are becoming essential consulting tools. Data-driven decision-making allows consulting companies to deliver more precise and actionable insights to clients by leveraging vast amounts of structured and unstructured data. Consulting firms are using AI-powered business intelligence platforms to extract patterns, predict market shifts, and offer real-time strategic recommendations. With AI playing a larger role in business operations, ethical concerns regarding bias, transparency and governance are growing, increasing demand from organisations get advice on developing responsible AI strategies.
Internally, firms are investing heavily in AI technologies to improve productivity, automate routine tasks and offer innovative solutions to clients. For example, large firms have developed custom AI tools to assist with tasks such as email drafting, data formatting and document summarisation, allowing their consultants to focus on higher value activities. It is a matter of time before AI applications are rolled out into HR and compensation, however, caution will be advised to ensure accuracy and effectiveness in implementing such ambitious, and often unproved, technologies.
3. Decentralised and Blockchain-Based Consulting Solutions
Blockchain technology is beginning to find a foothold beyond finance, into areas such as supply chain and healthcare. As organisations experiment with tokenisation and smart contracts, consultants are increasingly called upon to advise on regulatory compliance, risk management, and the practical integration of these technologies.
4. Private equity investment and industry consolidation
There has been a notable uptick in private equity interest in consulting firms. These investments are fuelling strategic acquisitions and partnerships, expanding market reach while also forcing traditional equity partnerships to adapt to new ownership models and the challenges of integrating disparate corporate cultures.
It is important to note that these investments also bring significant cultural changes and financial implications for the traditional equity partnerships, who have to adapt to new ownership structures or, for example stemming from the merger and integration of the consultancies being purchased. Implications are also expected for the talent pool, as new, expanding or restructured firms make their mark on the local employment market.
5. Focus on Resilience and Risk Management
In response to geopolitical uncertainties and economic fluctuations, advisory services focused on building organisational resilience and effective risk management are in high demand.
Key focus areas include, for instance, geopolitical and financial risk management, supply chain resilience, cybersecurity, ESG compliance, and crisis preparedness to ensure long-term business stability.
6. Sustainability and ESG Advisory
Sustainability is no longer an optional business practice but a core strategic priority. Environmental, social and governance (ESG) consulting is shifting from compliance-focused approaches to holistic business transformation strategies. At Vencon Research we see both this and the previous Risk Management trend substantiated in steadily increasing demand for compensation benchmarking related to consultant roles in these fields.
7. Growth of Corporate Out-of-House Firms and Independent Consulting
A continuing trend is strong growth of consulting offering stemming from consulting practices that were originally founded to consult their parent companies in-house, as well as from firms that were otherwise more strongly focussed on non-consulting actively. Examples include Detecon, DSS+, IQVIA and Mastercard, all of which are now both well respected and seen as serious alternatives to traditional consulting firms working in their field of expertise.
In parallel, we see a notable uptick in prominence for “independent” consultants, i.e. freelance or individual service providers, with clients attracted by the autonomy and flexibility this alternative offers. This growth is leading to the formation of new consortia and networks of independent consultants, allowing them to collaborate on larger projects and share resources.
Both of these trends will increase the realm and span of potential competitors to the traditional consulting organisations – with consequent effects on staffing and compensation.
8. Niche and Specialised Boutique Consulting
The trend continues that competition increases from boutique consulting companies specialising in emerging fields such as ESG compliance, AI ethics, and supply chain resilience. Firms offering deep industry or functional knowledge are in great demand from a broad spectrum of clients. Careful evaluation is called for when deciding whether to include such firms as competitors in a benchmarking exercise. It may be that a firm competes for talent with such boutiques in a given market, or, conversely, their relative size, pay structure, and business focus may result in a skewed perception of the wider market.
Broader Recruitment Strategies
While each of the above trends brings its own set of considerations to HR and talent management, one additional shared is found in a consulting landscape that is continually becoming more diverse. Firms are expanding their recruitment efforts beyond traditional MBA programmes to include candidates from non-target schools, specialised master's programmes, PhDs and experienced professionals to allow more for more effective recruitment. This applies whether in generalist or specialist roles.
Salary Trends
Reviewing our own market data and recently published external sources indicates a worldwide anticipated “average” increase in salary budgets of approximately 3.7% in 2025 (we include Vencon Research data in this projection as an average across all positions and countries in our database).
This rate is marginally lower than the increase that was observed in 2024. While the management consulting industry continues to offer very competitive remuneration packages, the rate of salary growth in 2025 reflects a cautious approach amid evolving economic conditions.
Interestingly, we have seen a higher increase in the salaries typically being offered to recruits coming from outside of the traditional MBA programmes but only limited increases to those candidates from within the traditional channels for recruitment.
Vencon Research – Independent Insights for Consulting Firms
Vencon Research provides data-driven analysis and benchmarking tailored to the consulting industry. With a focus on clarity and precision, their research helps firms refine compensation strategies, assess market trends, and make informed decisions. Learn more at venconresearch.com

Expanding Consulting Capabilities: Why More Firms Are Investing in Advisory Services
By Yao Tang - Business Development Manager
Companies across industries are expanding their consulting divisions through a mix of strategic acquisitions and internal growth. This trend is driven by the rising demand for integrated solutions, the pursuit of high-margin revenue, and the imperative to support clients through digital transformation. In this article, we explore the strategies behind these expansions, highlight key examples from various sectors, and discuss the HR challenges that arise when integrating consulting roles into existing compensation structures.
Expansion Across Sectors
The trend toward incorporating or expanding consulting capabilities is evident across a range of sectors—from technology to private equity, specialized industries, and traditional accounting—where companies are leveraging strategic acquisitions and internal growth to meet the rising demand for integrated, expert advisory services.
A. Technology Firms Moving Beyond IT Services
Technology companies are increasingly shifting from their traditional focus on IT services to broader consulting roles. For instance, NEC’s acquisition of ABeam Consulting in 2023 represents a strategic move to expand its advisory offerings. Similarly, in 2023, Accenture’s acquisition of InfinityWorks—a leader in agile digital transformation solutions—underscores the growing demand for integrated advisory services. In addition, other types of firms are also responding to this trend; for example, EY’s 2022 acquisition of Nuvalence has enhanced its digital transformation expertise, reflecting a broader industry move toward offering comprehensive, end-to-end consulting solutions.
B. Private Equity’s Interest in Consulting
Private equity firms are capitalizing on the high-margin revenue potential of consulting services. The ongoing discussions by Apax Partners to acquire a majority stake in CohnReznick, along with Inflexion’s 2025 acquisition of Baker Tilly Netherlands, reflect a broader trend of investing in professional services with established consulting practices. These moves are not only financial transactions but also strategic efforts to diversify revenue streams and build more resilient business models.
C. Specialized Industry Consulting
In specialized fields such as life sciences, biotech, and pharmaceuticals, targeted acquisitions have become a key strategy. Sia Partners’ 2022 acquisition of Latham BioPharm, for example, deepened its expertise in these sectors. By focusing on niche advisory services, firms can offer tailored solutions that address the specific regulatory and operational challenges inherent in these industries.
D. Accounting Firms Strengthening Their Advisory Services
Accounting firms have long offered professional advisory services, and many are now expanding these capabilities. PwC’s 2023 acquisition of Sagence boosted its data and digital transformation advisory, while Deloitte has expanded its digital consulting presence in both the U.S. and Europe. KPMG’s acquisition of Russell Reynolds Associates and Grant Thornton’s 2024 partnership with New Mountain Capital further underscore the trend of blending traditional accounting services with modern consulting approaches.
Key Drivers Behind the Expansion
Several factors are motivating firms to broaden their consulting capabilities:
- Digital and AI Expertise: The rapid adoption of technologies such as cloud computing, automation, and AI has created an urgent need for expert guidance. Consulting services now play a critical role in helping organizations navigate digital transformation.
- Revenue Diversification: Consulting provides recurring, high-margin revenue streams that complement other business areas. This diversification is particularly attractive in a volatile market environment.
- Client Demand for Integrated Services: Clients increasingly seek comprehensive, end-to-end solutions that combine strategic advice with practical implementation. Firms are responding by integrating consulting services into their broader offerings.
HR Challenges in Integrating Consulting Roles
Integrating consulting roles into established compensation structures presents several HR challenges:
1. Differing Compensation Structures
- Consulting Models: Often include performance-based bonuses, accelerated salary progression, and equity incentives at senior levels.
- Corporate Models: Typically rely on fixed salary bands and standardized annual raises.
- The Challenge: Balancing these models to avoid pay disparities while remaining competitive in both markets.
2. Incentives and Career Progression
- Consulting Firms: Employees expect rapid promotions and profit-sharing opportunities.
- Traditional Corporations: Generally emphasize structured career growth based on tenure.
- The Challenge: Designing career paths that attract top consulting talent without undermining traditional career progression models.
3. Recruitment and Retention
- Consulting Talent: Often drawn to project-based, performance-driven roles but tend to be more mobile.
- Corporate Talent: Typically prefer longer-term, specialized roles with predictable career paths.
- The Challenge: Crafting recruitment and retention strategies that effectively appeal to both types of professionals.
4. Accurate Benchmarking of Compensation
- Consulting Benchmarks: Usually compared against peer consulting firms.
- Corporate Benchmarks: Often aligned with industry-specific salary norms.
- The Challenge: Developing a hybrid benchmarking approach that reflects both consulting and corporate compensation standards to ensure internal equity and external competitiveness.
How Vencon Research Supports Compensation Strategy
Vencon Research plays a crucial role in helping firms navigate these HR challenges by providing detailed compensation benchmarking for consulting roles. With access to comprehensive market data, organizations can align their pay structures with industry standards while maintaining competitiveness and internal equity. Whether expanding a consulting division or restructuring compensation strategies, Vencon Research offers insights that support strategic growth and stability.
For more information on aligning your compensation strategy with industry standards, please contact Vencon Research to learn how our services can support your organization’s strategic objectives.


Benchmarking Data that Works
In order to make informed decisions about compensation packages in your field, you need the latest data at
your fingertips.